Author: The Team

  •  Case Study: Two-HMO Portfolio Sale in Folkestone 

     Case Study: Two-HMO Portfolio Sale in Folkestone 

    The Opportunity

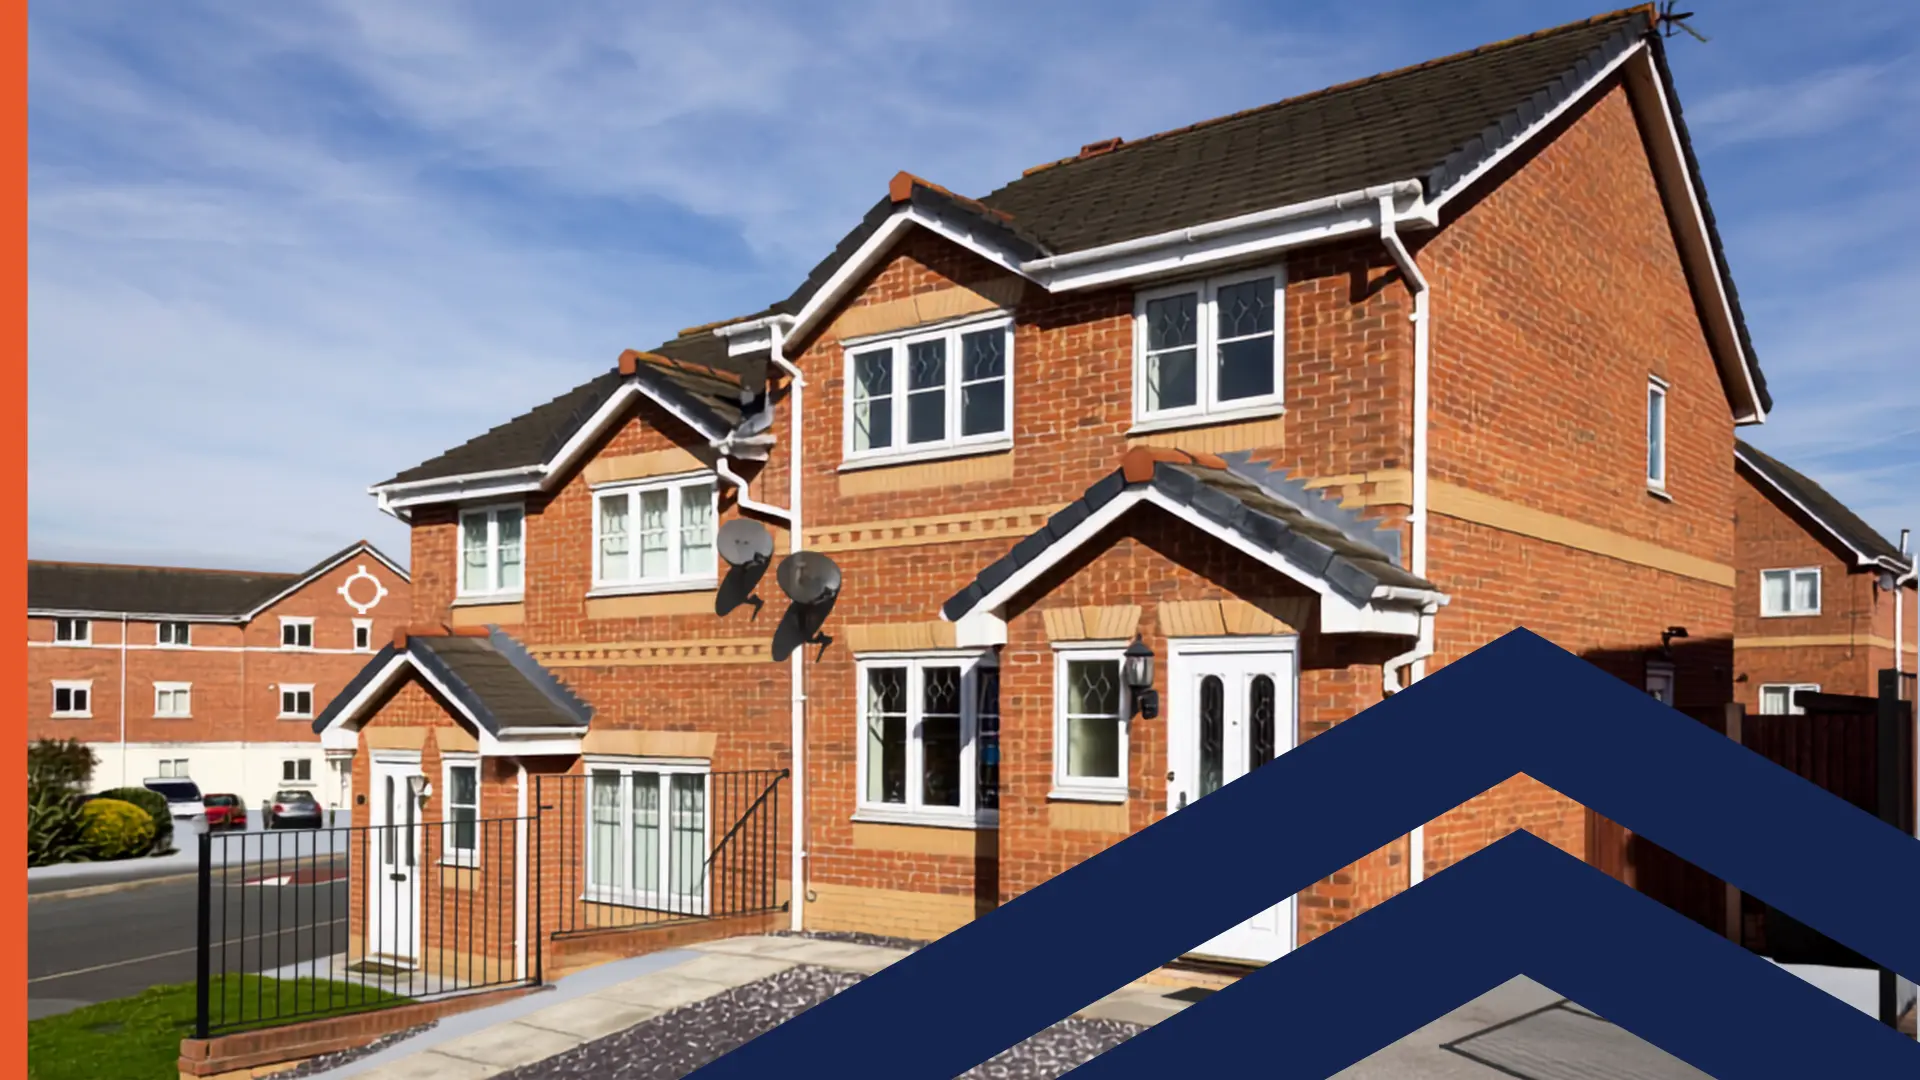
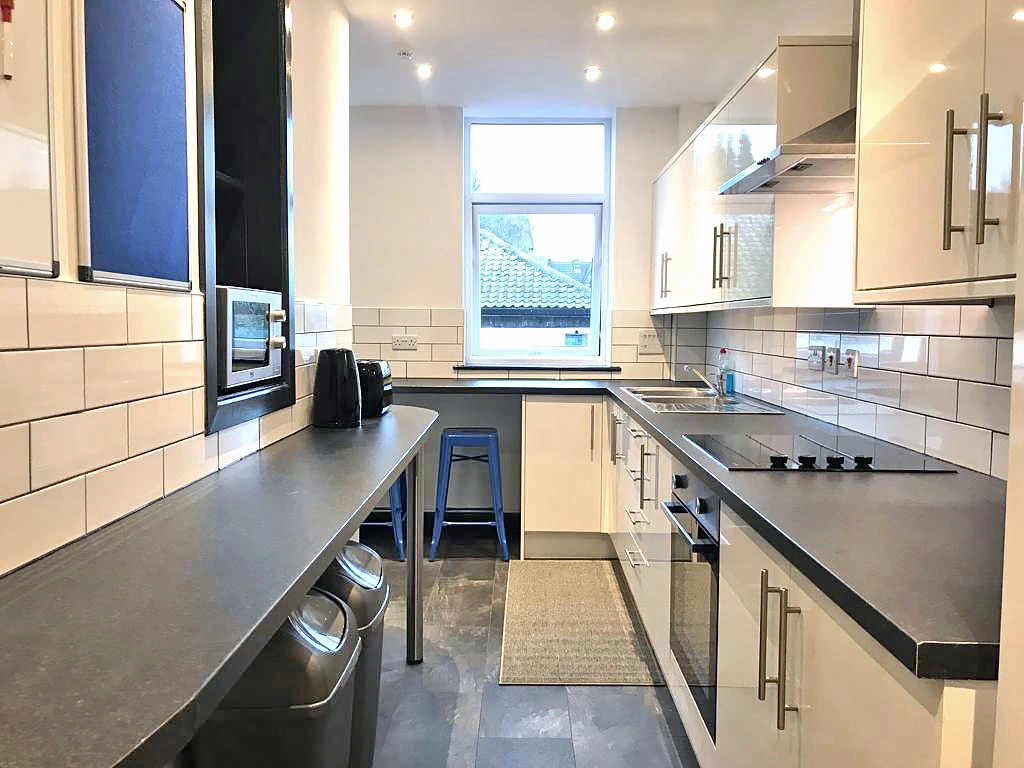
    We sold two neighbouring 6-bedroom HMOs in Folkestone to an investor we had been working with for around 12 months.

    Portfolio Highlights

    • Combined Asking Price: £645,000
    • Combined Estimated Value: £790,000
    • Annual Rental Income: £87,300
    • Combined Yield: 13.5%
    • Total Bedrooms: 12

    The first property was priced at £335,000, producing £47,580 per year at a 14.2% gross yield.

    The second was priced at £310,000, producing £39,720 per year at a 12.81% gross yield.

    Both were modern, well-presented HMOs and offered the buyer the opportunity to acquire a strong small portfolio in one location.

    The Challenge

    The sellers were based in Ukraine at the time, which made communication and managing the transaction more difficult.

    During legals, it also came to light that the correct HMO planning position was not fully in place.

    With the buyer’s mortgage offer approaching expiry, we had to work quickly.

    We helped coordinate planning professionals, the required application, improvements to the cycle storage and access to the properties, while working alongside the buyer, seller and solicitors to keep the deal alive.

    A legal arrangement was put in place to allow completion to proceed while the planning matter was finalised.

    Planning was subsequently approved.

    The Result

    After around a year of working with the buyer, we successfully completed the £645,000 acquisition of both HMOs, producing over £87,000 per year in rental income.

    The deal generated an approximately £12,000 sourcing fee, alongside a seller-side fee.

    More importantly, it demonstrates the value of staying involved throughout the entire transaction.

    We didn’t just introduce the deal. We helped manage the problems, coordinate the different parties and get a complicated transaction over the line.

  • UK House Price Growth Slows But What Does It Mean for Property Investors?

    UK House Price Growth Slows But What Does It Mean for Property Investors?

    The UK property market has entered the second half of 2026 at a slower pace, with annual house price growth easing to 1.3%.

    According to the latest Zoopla House Price Index, the average UK property has increased in value by around £3,400 over the past year, while the number of sales being agreed has fallen by 9% compared with the same period last year, but for property investors, the national headline only tells part of the story.

    At My Property Group, we’re far more interested in where the market is moving, where opportunities are emerging and what the changing conditions mean for investors looking to acquire property.

    The UK property market is becoming increasingly regional

    One of the clearest messages from the latest data is the growing difference between regional property markets. The North West has been one of the strongest-performing regions, with the average property increasing in value by approximately £7,100 over the past year. London, meanwhile, has moved in the opposite direction, with the average property falling by approximately £3,270. 

    It’s another reminder that there isn’t really one “UK property market”. Different towns, cities and even postcodes can offer completely different levels of affordability, rental demand, capital growth and investment potential. For investors, understanding those local fundamentals is becoming increasingly important.

    Buyers have more negotiating power

    There are also more properties available for sale across much of the country. Housing supply has increased in eight of the UK’s 11 regions, while almost a third of properties listed since Q2 remain unsold without having undergone a price reduction. For homeowners, that can make for a more challenging selling environment. For investors who are ready to purchase, however, it can create opportunity.

    More stock, slower transaction volumes and motivated sellers can provide buyers with greater negotiating power, particularly where a property has been incorrectly priced or has remained on the market for an extended period.

    This doesn’t mean every discounted property represents a good investment, it means well-researched investors may have more room to negotiate.

    Property type matters too

    The difference isn’t only geographical, different types of property are also performing differently. Average values for flats and maisonettes have fallen by 1.7% year-on-year, while terraced properties have increased by 1.7%, semi-detached homes by 1.9% and detached properties by 1%.

    Again, the important question for an investor isn’t simply whether property prices nationally are rising or falling. It’s whether a particular property, in a particular location, works as an investment. That means considering purchase price alongside rental demand, achievable rent, yield, financing, refurbishment requirements, running costs and the longer-term prospects of the area.

    Higher mortgage rates are affecting the market

    Borrowing costs continue to influence buyer behaviour. Mortgage rates fell from almost 5% in April to around 4.65% in June before increasing again to approximately 4.75% during July.

    According to Zoopla, changes in rates since the beginning of the year have added approximately £125 per month to repayments for a typical buyer. For investors using finance, that makes the numbers behind an acquisition even more important. A deal shouldn’t work because you’re relying on interest rates falling in the future; it needs to be assessed against today’s financing costs, realistic rental income and the costs associated with owning and operating the property.

    Could the slower market create opportunities for investors?

    Potentially; a slower property market doesn’t necessarily mean a bad property market for investors. In certain areas, reduced competition and greater seller motivation can create opportunities to acquire property at more attractive prices.

    But selectivity also matters, with house-price performance varying substantially across the UK, investors need to look beyond national averages and understand the fundamentals behind individual locations and deals.

    Where is rental demand coming from? What yield can realistically be achieved? Is there an opportunity to add value? What are comparable properties actually selling and renting for? Does the investment still work if market conditions remain relatively flat?

    These are much more useful questions than simply asking whether UK house prices are going up.

    What happens next?

    Zoopla expects property-market activity to increase from September following the traditional summer slowdown, provided mortgage rates remain relatively stable.

    However, annual house-price growth is expected to slow towards approximately 1% by the end of 2026, with stronger performance anticipated across parts of Northern England and Scotland while London and the South East could experience flat or modestly falling prices.

    For investors, that creates a market where research, deal selection and buying at the right price become increasingly important.

    Finding opportunities in today’s property market

    At My Property Group, we believe successful property investment starts with the deal but doesn’t end there. Through our network, we connect investors with property opportunities from across the UK while supporting the wider investment journey, from sourcing and due diligence through to finance, conveyancing, refurbishment, lettings and ongoing portfolio growth.

    The market may be changing but the opportunity is all about understanding where to look.

    Market statistics referenced in this article are based on the Zoopla House Price Index, July 2026.
  • Case Study: £865,000 18-Bed HMO Co-Sourced Through Our White Label Network

    Case Study: £865,000 18-Bed HMO Co-Sourced Through Our White Label Network

    Shelton Old Road, Stoke-on-Trent

    Purchase Price: £865,000
    Annual Rental Income: £106,320
    Gross Yield: 12.2%
    Property Type: 18-Bedroom HMO
    En-Suite Bedrooms: 18
    Tenure: Freehold

    This transaction is a great example of how the My Property Group White Label Partnership model works in practice combining the relationships of our partners with the sourcing, sales, negotiation and deal progression infrastructure of the wider My Property Group team.

    The Opportunity

    Scott C joined My Property Group as a White Label Partner towards the end of 2025, one of the biggest advantages of the White Label model is that our partners don’t need to source, negotiate and progress every property transaction themselves.

    Their primary role is simple:

    Build relationships with investors and bring qualified buyers into the business.

    Our team can then support with the property, seller relationship, viewings, negotiation, sourcing process and progression through to completion. The Shelton Old Road transaction demonstrates exactly that.

    Introducing the Buyer

    Scott introduced an investor who was actively looking to acquire a substantial HMO investment.

    The buyer initially reserved a different HMO opportunity through us. However, after reviewing the property further, he decided that it wasn’t the right investment for him. Rather than losing the buyer, the team immediately looked at alternative opportunities that better matched what he was looking for.

    One of those opportunities was Shelton Old Road in Stoke-on-Trent, an established 18-bedroom HMO producing £106,320 per annum in rental income.

    The property offered:

    • 18 fully en-suite bedrooms
    • £106,320 annual rental income
    • 12.2% gross yield
    • Freehold ownership
    • An established HMO investment strategy
    • Significant rental income from day one

    The buyer viewed the property and immediately saw the potential.

    Bringing the Deal Together

    From there, the My Property Group infrastructure took over. Joe, from our Listings Team, managed communication with the seller and coordinated the property viewings. Scott then handed the investor across to Jamie, from the Sales Team, who worked directly with the buyer while Joe continued managing the seller relationship.

    Between the two sides, the team negotiated and agreed a final purchase price of:

    £865,000

    Once both buyer and seller were happy with the terms, the transaction moved forward.

    £20,760 Sourcing Fee Generated

    Our agreed sourcing fee on the transaction was 2.4% of the purchase price, generating a total sourcing fee of:

    £20,760

    The fee was structured across two stages.

    On Offer Agreed

    The buyer paid the first 50% of the sourcing fee:

    £10,380

    Once received, Scott received his agreed White Label Partner share of that payment.

    On Completion

    The remaining:

    £10,380

    was collected when the transaction successfully completed, with Scott again receiving his agreed share.This structure meant both My Property Group and the White Label Partner were financially aligned around successfully progressing the transaction through to completion.

    From Offer Agreed to Completion

    Once the property entered the legal process, our Deal Progression Team stepped in. Marta, our Deal Progressor, worked alongside the buyer, seller, solicitors and wider parties involved in the transaction to help keep everything moving towards completion. Scott didn’t have to become the buyer’s solicitor, chase every party involved or personally manage the transaction from start to finish. He had done one of the most important parts of the process by introducing the buyer.

    Our internal team then provided the infrastructure required to help turn that introduction into a successfully completed £865,000 property transaction.

    Why This Deal Represents the White Label Model

    This transaction is one of our strongest examples of what a successful co-sourced property deal can look like. Scott brought the relationship, My Property Group brought the property, seller relationship, listings infrastructure, viewings, sales support, negotiation and deal progression. Together, we completed an £865,000 HMO acquisition and generated £20,760 in sourcing fees.

    That’s the model. White Label Partners don’t need to build an entire property sourcing operation behind the scenes. They can focus heavily on what they do best; finding, building and maintaining relationships with property investors.

    When they identify a serious buyer, they can leverage the wider My Property Group platform to help find the right opportunity and take the transaction from introduction through to completion.

    The Deal at a Glance

    £865,000 Purchase Price
    18 En-Suite Bedrooms
    £106,320 Annual Rental Income
    12.2% Gross Yield
    £20,760 Total Sourcing Fee Generated
    White Label Partner: Scott C
    Sales: Jamie
    Listings & Seller Management: Joe
    Deal Progression: Marta

    For our White Label Partners, Shelton Old Road is exactly the type of transaction we want the network to replicate. A partner introduced a qualified investor, our team provided the deal and infrastructure. Together, we negotiated, progressed and completed the transaction.

    You bring the buyer and we’ll help you do the rest.

  • Renters’ Rights Act 2026: What Landlords Need to Know Ahead of the 1st of May

    Renters’ Rights Act 2026: What Landlords Need to Know Ahead of the 1st of May

    As we approach the implementation of the Renters’ Rights Act on 1st of May 2026, it is important that landlords take the time to fully understand the upcoming legislative changes and how they will impact the management of their properties.

    This is one of the most significant reforms to the private rental sector in recent years. While many of the changes are designed to improve standards and transparency across the industry, they will also introduce new responsibilities and require a more structured approach to lettings.

    We strongly encourage all landlords to review the official government guidance in full:
    https://housinghub.campaign.gov.uk/renting-is-changing/

    In the meantime, we have outlined the key updates below, along with what they mean in practical terms for you as a landlord.

    A More Structured Lettings Environment

    The overarching aim of the Renters’ Rights Act is to create a more consistent and transparent rental market for both landlords and tenants.

    From a landlord’s perspective, this means:

    • A greater emphasis on compliance and documentation
    • More defined legal processes when managing tenancies
    • Increased scrutiny from local authorities

    While these changes may require adjustments to existing processes, they also provide an opportunity to adopt a more professional and robust approach to property management.

    Abolition of Section 21

    From 1st of May 2026, Section 21 ‘no fault’ evictions will be abolished.

    This means that landlords will no longer be able to regain possession of a property without providing a valid legal reason.

    Instead, possession must be sought under revised Section 8 grounds, which include:

    • Persistent rent arrears
    • Anti-social behaviour
    • Intention to sell the property
    • Landlord or family occupation

    What this means for landlords:

    • Clear evidence and documentation will be essential
    • Tenancy management must be more proactive
    • Regaining possession may take longer if processes are not followed correctly

    End of Fixed-Term Tenancies

    All assured shorthold tenancies will transition to periodic (rolling) agreements.

    There will no longer be fixed-term contracts with defined end dates.

    In practice:

    • Tenancies will continue until either party gives notice
    • Landlords will need to rely on valid possession grounds rather than fixed-term endings
    • Greater focus will be placed on maintaining positive tenant relationships

    Rent Increase Regulations

    The new legislation introduces stricter controls on how and when rent can be increased.

    From May 2026:

    • Rent can only be increased once per year
    • A formal notice period must be provided
    • Increases must reflect market value
    • Tenants will have the right to challenge increases through a tribunal

    Additionally:

    • Rental bidding wars will be prohibited
    • Restrictions will apply to requesting rent in advance

    Landlord considerations:

    • Rent reviews should be planned carefully and supported by market data
    • Transparency in pricing will be essential

    Tenant Rights and Responsibilities

    The Act also introduces several measures aimed at creating a fairer and more accessible rental market.

    These include:

    • A requirement to reasonably consider tenant requests to keep pets
    • A prohibition on discrimination against tenants with children or those in receipt of benefits
    • Mandatory provision of written tenancy information, including a government-issued Information Sheet

    While these changes enhance tenant rights, it is important to note that tenants remain responsible for:

    • Meeting their rental obligations
    • Complying with tenancy terms
    • Maintaining the condition of the property

    Compliance and Enforcement

    The new framework will be supported by increased enforcement powers for local authorities.

    Landlords should be aware that:

    • Financial penalties for non-compliance can be significant
    • Rent repayment orders are being strengthened
    • Record-keeping and legal compliance will be more closely monitored

    As a result, ensuring that all documentation, processes, and communications are in line with current legislation will be essential.

    Preparing for the Changes

    As your letting agent, our role is to support you through this transition while continuing to act in accordance with your instructions.

    In preparation for the 1st of May implementation, we recommend:

    • Reviewing your current tenancy agreements and processes
    • Familiarising yourself with the updated possession grounds
    • Ensuring all documentation is accurate and up to date
    • Considering how these changes may impact your portfolio strategy

    We will continue to monitor developments and provide further updates as additional guidance is released.

    What does all this mean for you?

    The Renters’ Rights Act represents a significant shift in how the private rental sector operates.

    While the changes introduce new requirements, they also aim to create a more balanced and transparent system for all parties involved.

    Taking the time to understand and prepare for these updates now will help ensure a smooth transition and reduce the risk of disruption once the legislation comes into effect.

    If you would like to discuss how these changes may affect your property or portfolio, please do not hesitate to get in touch.

  • Rightmove Is Now Integrated With ChatGPT: What This Means for UK Property Investors

    Rightmove Is Now Integrated With ChatGPT: What This Means for UK Property Investors

    A quiet but very important update just happened in the UK property space. Rightmove has officially launched an integration with ChatGPT, allowing users to discover property listings directly through conversational search inside ChatGPT. At first glance this might sound like just another tech update but in reality, it signals a much bigger shift in how property will be discovered, analysed and purchased in the future.

    The Shift From Search to Conversation

    Traditionally, property search has been very manual. Investors would go onto portals like Rightmove or Zoopla, filter locations, adjust price ranges, and scroll through hundreds of listings.

    Now imagine instead asking:

    “Show me 3-bed family homes near Leeds with strong rental demand under £450k.”

    Within seconds, AI can surface relevant listings. This changes property search from filtering websites to having conversations with data.

    For investors, this means:

    • Faster deal discovery
    • Smarter property filtering
    • Less time manually searching portals

    What This Means for Property Investors

    This type of integration will accelerate a trend we’ve already been seeing for a while.

    Investors are increasingly using AI tools to:

    • Analyse deals
    • Compare rental yields
    • Research areas
    • Identify undervalued opportunities

    When platforms like Rightmove start connecting directly with AI tools, it becomes far easier to move from idea to opportunity to investment decision.

    Instead of manually researching areas, investors will be able to ask:

    • “Where are the best yields in the North East right now?”
    • “Show me HMOs under £250k within the commuter distance of Manchester.”
    • “Find properties with refurbishment potential in Leeds.”

    Why This Matters for the UK Property Market

    The UK property market has historically been slow to adopt new technology.

    But this integration shows the industry is starting to move toward a more data-driven and AI-enabled investment landscape. For serious investors, that creates two clear opportunities:

    1️⃣ Better deal sourcing – AI will make it easier to surface opportunities faster than ever before.

    2️⃣ Smarter decision making – investors can combine market data, rental trends and local insights much more efficiently.

    Those who learn to use these tools early will likely have a significant advantage.

    The Bigger Picture

    The investors who succeed over the next decade won’t just be the ones with the most capital.They will be the ones who know how to use data and technology to move faster than everyone else. AI won’t replace property investors but it will replace investors who don’t adapt.

    So, What Does This Mean at My Property Group?

    At My Property Group we’re already seeing how technology is transforming the way investors find and secure deals. Access to the right opportunities combined with the right information has never been more important. And tools like AI are only going to make the gap between informed investors and passive investors even bigger. The future of property investing isn’t just about location anymore. It’s about information and speed.

  • UK House Prices Hold Steady in February 2026: What the Latest Rightmove Data Means for Property Investors

    UK House Prices Hold Steady in February 2026: What the Latest Rightmove Data Means for Property Investors

    The latest Rightmove House Price Index shows that UK house prices remained virtually unchanged in February 2026 with the average asking price of newly listed homes standing at £368,019. While this may appear to signal a slowing market, the underlying data suggests something very different especially for property investors looking to secure opportunities in the current cycle.

    At My Property Group, we analyse market trends through an investment lens. Here’s what the latest figures really mean for investors and why 2026 could present one of the most strategic buying environments in recent years.

    UK House Price Trends 2026: Stability Signals Opportunity

    Despite even prices in February, asking prices have risen by 2.8% since December marking the strongest start to a year for UK house prices since 2020.

    For property investors, a stable market often creates stronger entry points than rapid price growth.

    When house prices stabilise:

    • Sellers become more realistic on pricing.
    • Negotiation opportunities increase.
    • Investors can focus on yield and long-term strategy rather than short-term competition.

    Rather than a slowdown, current market conditions indicate a phase of recalibration following early-year confidence returning after budget uncertainty.

    Is 2026 a Good Time to Invest in UK Property?

    One of the most significant insights from the Rightmove study is the improvement in affordability across the UK housing market, a key factor driving investor confidence.

    Key indicators include:

    • Average two-year fixed mortgage rates fell to around 4.28%, down from 4.96% a year ago.
       
    • Average earnings rising by 4.7% year-on-year, outpacing recent property price growth.
    • Lenders offer more flexible borrowing options and higher income multiples.

    For investors, improved affordability doesn’t just benefit buyers; it supports future resale demand, tenant stability and long-term asset performance.

    More Homes on the Market Creates a Stronger Buying Window

    The Rightmove report highlights that the number of homes for sale is currently at an 11-year high for this time of year. Increased housing supply is often viewed negatively in mainstream headlines but for property investors it can be highly advantageous.

    Higher stock levels mean:

    • Greater choice across different asset types.
    • Reduced competition compared with peak market periods.
    • Increased ability to negotiate on price and terms.

    This environment particularly benefits investors targeting HMOs, refurbishment projects or off-market opportunities where strategic sourcing can create long-term value.

    Mortgage Rates and Lending Conditions: A Key Signal for Investors

    Mortgage affordability continues to improve with rates remaining close to their lowest levels since the 2022 mini-budget.

    Lower borrowing costs influence investor behaviour in several ways:

    • Improved cash flow on leveraged investments.
    • Increased buyer demand, supporting market liquidity.
    • Greater access to refinancing opportunities.

    For investors using bridging finance or commercial strategies, stable rates provide additional confidence when planning medium-term to long-term projects.

    What the February 2026 Housing Market means for Property Investment Strategy

    From an investment perspective, the latest data points towards a market driven by fundamentals rather than speculation.

    Key trends investors should be watching include:

    1. Negotiation Power is Returning

    With increased housing supply, investors have more leverage to structure deals effectively.

    2. Market Confidence is Rebuilding

    Buyer sentiment improved significantly after early-year uncertainty, supporting transaction activity.

    3. Strategy Matters More Than Timing

    Instead of chasing rapid appreciation, investors are likely to benefit most from current conditions when they focus on the following:

    • High-yield assets
    • Value-add refurbishments
    • Off-market acquisitions

    My Property Group’s outlook for the UK property market in 2026

    Based on the latest Rightmove data and wider market trends, we believe 2026 presents a strategic window for investors.

    Stable pricing, improving affordability and increased stock levels are creating an environment where disciplined investors can secure strong long-term opportunities particularly through private sourcing networks and off-market acquisitions.

    While headline figures suggest a quiet month, the underlying market fundamentals remain positive for those positioned correctly.

  • Autumn 2025 Budget: What It Means for Property Investors & Landlords

    Autumn 2025 Budget: What It Means for Property Investors & Landlords

    Higher tax on rental & property income (from 2027)

    • Rental income will be taxed at higher rates.
    • Basic-rate landlords now pay 22% instead of 20%, higher-rate pay 42% instead of 40%.
    • This reduces net profits for anyone holding property in their personal name.

    High-value property surcharge (“mansion tax”) from 2028

    • Properties worth £2M+ will face an annual surcharge, similar to extra council tax.
    • Investors holding premium or high-value homes will see increased ongoing costs.

    Dividends & investment income taxed more

    • Higher dividend and savings tax will affect investors who:
      • Own property through a limited company
      • Take income via dividends
    • This makes extracting money from company-owned portfolios more expensive.

    What This Means for Property Investors & Landlords

    1. Lower Net Returns

    • Higher taxes on rental income mean reduced cashflow.
    • HMOs, BRRs and higher-yield strategies become more attractive compared with standard BTL.

    2. High-value assets less attractive

    • The surcharge on £2M+ homes increases holding costs, pushing investors toward:
      • Northern cities
      • Smaller units
      • Higher-yield stock

    3. Possible increase in landlord exits

    • Some landlords with low-yield or highly leveraged properties may sell up due to reduced profitability.

    4. Bigger focus on tax-efficient structuring

    • Many landlords will re-evaluate:
      • Company structures
      • Refinancing
      • Portfolio reshaping
      • Moving away from personal-name ownership

    5. More demand for yield-driven deals

    • Investors will now push toward:
      • HMOs
      • Flats under £150–200k
      • BRR opportunities
      • High-cashflow regional markets

    The Big Picture

    The Government is intentionally shifting the tax burden onto property income and high-value property ownership.

    For landlords and investors, this means:

    • Be more selective with what you buy
    • Re-analyse your portfolio
    • Focus on yield, not speculation
    • Consider corporate structures for tax efficiency
  • Autumn 2025 Budget: What Property Investors Need To Know

    Autumn 2025 Budget: What Property Investors Need To Know

    The Autumn 2025 Budget is coming soon, and based on what’s already been announced and leaked, here’s a quick, clear guide on what it could mean for property investors and tenants.

    The Good News for Investors

    1. More motivated sellers (especially higher-value homes)

    The government is planning to raise taxes on expensive homes. This might push some owners to sell sooner meaning better deals and potential discounts for investors.

    2. Still strong opportunities in cheaper, high-yield areas

    If you invest in sub-£300k properties, HMOs, BRR projects, or regional markets, this Autumn Budget doesn’t hit you as hard. Cashflow-focused deals stay strong.

    3. Company structures become even more attractive

    If new taxes hit personal landlords, limited companies may become the more tax-efficient route. Good news if you already buy this way.

    The Bad News for Investors

    1. Higher council tax on expensive homes

    Expect higher ongoing costs for Band F–H properties and £1m+ homes. If you hold big single lets or high-value stock, your profit may reduce.

    2. Possible National Insurance on rental income

    One of the biggest rumours: landlords may have to pay NI on rental profits. This would reduce net income for anyone owning property in their personal name, especially if heavily mortgaged.

    3. Stamp duty and CGT could tighten again

    The government needs to raise more money, so additional property taxes could increase. This mainly impacts people flipping or selling regularly.

    The Impact on Tenants

    This Budget isn’t just about landlords, tenants will feel it too.

    1. Lower energy bills (potentially)

    There’s talk of cutting green levies and reducing energy-related VAT. If that happens, tenants could see slightly cheaper monthly bills.

    2. Pressure if landlords exit the market

    If taxes rise too much and smaller landlords sell up, the rental market could become:

    • More competitive
    • More expensive
    • With less available stock

    3. EPC + energy efficiency uncertainty

    If the government reduces funding for green upgrades, landlords may delay improvements. This means some older rental homes might stay less energy efficient for longer…not great for tenant comfort or bills.

    So… is this Autumn Budget good or bad?

    It’s tougher for investors who own expensive homes, are highly leveraged, or hold properties in their own name.

    But it’s not all bad news investors who:

    • Buy well
    • Add value
    • Focus on yield
    • Use company structures

    They’re likely to still do well, and may even benefit from more motivated sellers and less competition.

    My Property’s Group’s Advice Right Now

    • Run your numbers again – assume slightly higher tax and council tax.
    • Focus on high-yield deals – BRR, HMOs, and strong regional rentals.
    • Consider using a company for new purchases.
    • Keep some cash/borrowing power ready – good opportunities may appear after the Autumn Budget.
    • Support tenants where possible – lower arrears and fewer voids will matter even more if taxes rise.

    The Chancellor of the Exchequer, Rachel Reeves, will deliver the Autumn Budget on Wednesday 26th November.

  • The ‘Too Late’ Myth: Why Now Is the Perfect Time to Start in UK Property

    The ‘Too Late’ Myth: Why Now Is the Perfect Time to Start in UK Property

    If you’ve been watching the UK property market from the sidelines, you’ve probably asked yourself: “Have I missed the boat?”

    It’s one of the most common concerns among would-be investors — and it’s fuelled by headlines about rising prices, higher interest rates, and an uncertain economy. But here’s the truth: the ‘too late’ myth is just that — a myth.

    In reality, there’s never been a “perfect” moment to start in property. Every era has its challenges and its opportunities. The key is knowing how to spot them. And in 2025, there are more opportunities than you might think.

    1. Strong Rental Demand Has Never Been Higher

    The UK is facing a structural shortage of housing. Demand for rentals is at record highs, driven by:

    • Affordability challenges keeping first-time buyers out of the market.
    • Changing lifestyles, with tenants seeking flexibility over long-term commitments.
    • The remote and hybrid work shift, expanding demand in commuter towns, suburbs, and semi-rural areas.

    As of late 2024, UK rents were up 9% year-on-year, significantly outpacing wage growth. For investors, that means strong yields and consistent cash flow.

    2. Market Resilience in the Face of Headwinds

    Yes, interest rates are higher than the ultra-low era of the 2010s — but the property market has remained remarkably stable. House prices in many regions are holding or even growing, supported by low supply and strong demand.

    Savvy investors know this: volatility creates opportunity. While some are waiting for “the perfect time,” others are securing deals now, often with more negotiation power as sellers adjust expectations.

    3. Regional Hotspots Are Outperforming the Headlines

    National averages can be misleading. While London’s growth may have slowed, cities like Manchester, Leeds, and Birmingham are seeing strong rental yields and tenant demand.

    In Manchester, for example, average yields hit 6.5% in April 2024, with high-performing areas reaching 12% — well above the national average. The right location can deliver returns that outweigh broader market concerns.

    4. EPC Regulations Are Creating a Window of Opportunity

    By 2030, rental properties in England and Wales will need an EPC rating of C or above. While this may seem like a hurdle, it’s also a chance to future-proof your portfolio and target properties others are overlooking.

    Many landlords are selling older stock rather than upgrading — which means motivated sellers and lower purchase prices for investors willing to make improvements.

    5. Technology Is Making Property Investment More Accessible

    From online sourcing platforms to digital property management tools, it’s never been easier to research, acquire, and manage investments.

    Technology now allows even first-time investors to:

    • Analyse deals in minutes.
    • Manage properties remotely.
    • Access fractional ownership opportunities with lower capital outlay.

    This accessibility is shrinking the gap between experienced landlords and newcomers.

    Why ‘Waiting’ Often Costs More Than Starting

    It’s easy to think that sitting on the sidelines is the safe option — but in property, time in the market beats timing the market almost every time. The longer you wait, the more you risk:

    • Missing out on rental income
    • Losing potential capital growth
    • Competing in a more expensive market later

    Even in a high-interest environment, the combination of rental returns, long-term appreciation, and inflation protection makes property a compelling asset class.

    The Bottom Line

    There will always be reasons to hesitate but the truth is, today’s market offers a unique blend of high rental demand, negotiable purchase prices, and powerful technology to help investors thrive.

    The ‘too late’ myth stops people from taking action. The investors who succeed are those who start — learn — and adapt.

    If you’ve been waiting for the perfect time to begin, here’s your sign: it’s now.

    If you want, I can also create a short, high-impact social media version of this post with bold stats and hooks to drive people to your blog. That way you can use it for LinkedIn, Instagram, and Facebook to get more eyes on it.

  • Stamp Duty Shake-Up: What Rachel Reeves’ Property Tax Plans Could Mean for You

    Stamp Duty Shake-Up: What Rachel Reeves’ Property Tax Plans Could Mean for You


    Chancellor Rachel Reeves is weighing up a major change for the Autumn Budget: replacing stamp duty with a new property tax. Here’s what’s on the table — and crucially, what it means if you’re a property investor.

    The proposals in a nutshell

    Stamp duty replacement: A proportional property tax, payable on sales of homes over £500k. Unlike the current stamp duty regime, this would affect around 20% of transactions, rather than 60%.

    Council tax overhaul: An eventual shift to a local, annual property tax based on current property values, finally replacing outdated 1991 council tax bands.

    Capital gains reform: Potential removal of the primary residence exemption for homes above £1.5m, which could mean CGT rates of 18–24% even on your main home when sold.

    Why investors should pay attention


    Property investors sit at the intersection of all three reforms — and the ripple effects could be big:

    Market activity & liquidity
    A move away from heavy upfront stamp duty could increase transaction volumes, making it easier to buy and sell property without a huge cash hit at purchase but uncertainty over thresholds (e.g. £500k) may stall deals short-term, especially in London and the South East.

    Holding vs. trading strategies
    If an annual property tax linked to value is introduced, the economics of holding long-term could change. Investors with high-value assets may see their yearly costs rise significantly, impacting yield.
    For leveraged investors, higher ongoing costs could tighten cashflow. Expect more scrutiny of ROI and potential pressure to rebalance portfolios towards higher-yielding regions.

    Tenant demand & rent levels
    If costs rise for landlords, some will look to pass these on through rents. But local markets will dictate how much is possible without pricing tenants out.
    A shift to proportional property taxes could also encourage downsizing, releasing more family homes into the rental and sales market — which might impact tenant demand dynamics.

    Exit strategies & capital gains
    For those planning to sell high-value properties, capital gains reform could bite into profits. This may accelerate some investors’ exit plans before changes are confirmed.
    On the flip side, if stamp duty is scrapped, selling to owner-occupiers could become more attractive, as buyers face a lower upfront barrier.

    What investors should be looking out for

    The Autumn Budget (expected late October/early November) — this is when we’re likely to see clarity on stamp duty reform.
    Regional implications — properties in London and the South East will be hardest hit by any £500k+ threshold. Northern investors with lower-value stock may actually benefit.

    Portfolio strategy — investors need to revisit models: factoring in not just purchase taxes, but potential annual levies and changing exit taxes.

    Key takeaways for you as a property investor

    For investors, Reeves’ proposed reforms are a double-edged sword:

    Positive: lower entry costs could stimulate activity and open up new opportunities.
    Negative: higher ongoing costs and CGT changes could hit long-term profitability.

    The winners will be those who stay agile — re-running their numbers, considering regional diversification, and being ready to act fast once the details are confirmed.

  • That’s a Wrap: August News from MPG and the Industry

    That’s a Wrap: August News from MPG and the Industry

    Welcome to our August wrap-up — your monthly snapshot of what’s shaping the investment property space and what’s been happening behind the scenes here at My Property Group.

    As always, our goal is to keep you, our partners, in the know, connect you with the right opportunities, and share a little of what life’s like inside the MPG team.

    So what’s going?

    Interest rates fell

    The Bank of England’s MPC voted by a narrow 5–4 margin to cut the base rate to 4%, the lowest it’s been in almost two years. After sitting at 5.25% between August 2023 and August 2024, we’re finally seeing a gradual easing.

    This matters because lenders are already adjusting products, which could unlock new possibilities for investors looking to refinance or expand their portfolios.

    Read our full blog post: Bank of England Cuts Base Rate to 4% – What It Means for Property Investors

    Social housing remains a hot topic

    With 1.3m households on waiting lists across England (Shelter, Feb 2025). Supply isn’t keeping up — just 650 homes were lost last year, fewer than 20,000 new builds were completed, and in London, new project starts have dropped 76% despite £11.7bn in government funding.

    For housing associations, new regulations on safety and maintenance are increasing costs and slowing delivery — creating pressure but also opening the door for collaboration. For our investors, sourcers, and partners, this is where My Property Group plays a vital role. With our in-house expertise and established relationships, we help our network connect with local authorities, housing associations, developers, and funding partners to bring forward viable projects. Our goal is to support the wider effort to address the housing shortage while helping our partners maximise opportunities in a responsible and sustainable way.

    Stamp Duty and other Property Taxes

    Chancellor Rachel Reeves is weighing major tax changes in the upcoming Autumn Budget that could reshape the property landscape. Here’s what’s on the table:

    • Stamp Duty Replacement → A proportional property tax on home sales over £500k, affecting ~20% of transactions.
    • Council Tax Overhaul → Moving to an annual local property tax based on current values, replacing outdated 1991 bands.
    • Capital Gains Reform → Potential removal of the primary residence exemption for homes above £1.5m, meaning CGT rates of 18–24% could apply even on main homes.

    For investors, these changes could have big implications for strategy and timing. Read our full blog post on what this mean for you as a property investor here.

    Reintroducing webinars

    We’ve brought back webinars, all led by our team, and we covered some really exciting topics in August:

    • Using your black book to unlock new opportunities
    • Power networking to build those key connections
    • Leveraging social media for maximum outreach
    • Creating lead magnets that actually convert

    It’s all about giving you the tools to succeed, and we’re really looking forward to having more of these conversations with you!

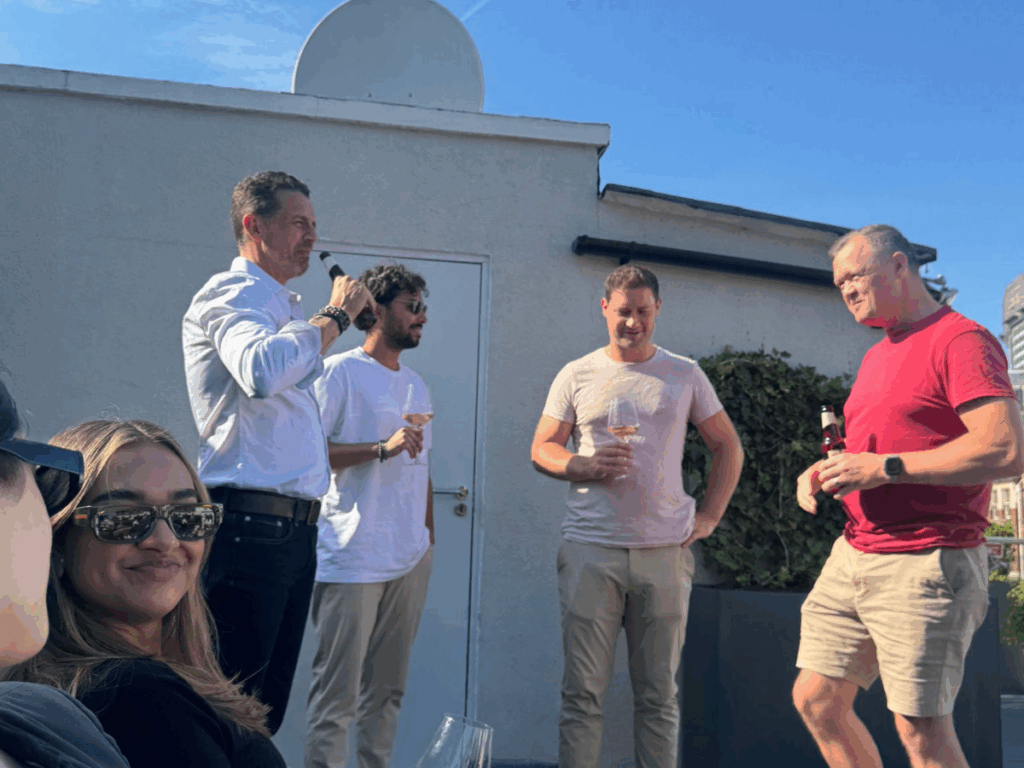
    MPG Office Summer Social

    All work and no play isn’t our style at MPG, so we made the most of the beautiful summer sunshine and headed to the office rooftop for some post-work drinks.

    Introducing the Private Wealth Desk: Bespoke Property Investment for You

    For serious investors, the best property deals move fast. That’s why we created the Private Wealth Desk, offering you exclusive access to off-market opportunities 24 hours before anyone else. Designed for investors with £200,000+ to deploy, we provide more than just deals — we offer personalized strategy, expert guidance, and hands-on support to help you build long-term wealth. From investment consultants to social housing specialists and financial planners, your dedicated team works alongside you to craft a portfolio that delivers sustainable returns.

    With proven success stories, like helping a client secure £12 million in property and 50% ROI in just six months, the Private Wealth Desk is your gateway to smarter, more profitable investments. We’re here to give you confidence, clarity, and a real edge in today’s competitive market.

    With Flair Agency

    We’re excited to share that Flair has officially joined forces with My Property Group! Flair (spearheaded by Company Director Ellis and new Marketing Manager, Abi) has built a strong reputation for creative, results-driven digital marketing—covering everything from paid search and SEO to full campaign strategies. By bringing Flair into the MPG family, we’re not only strengthening our digital offering, but also expanding beyond property into sectors like sport and healthcare. This move allows us to offer even more flexible and innovative marketing solutions to our clients, wherever they operate. It’s a big step forward, and we can’t wait to show you what’s next.

    MPG All-Stars

    If you ask Timmy what he does after work, he’s probably at one of his many football projects, be that playing, coaching or managing. He’s been instrumental in setting up the MPG All-Stars team here and they kicked off in style with their first game as a team ending in a 12-11 victory with Joe and Slade on fire in front of goal.

    Behind the Scenes: Media Day with Jamie and Joe

    Jamie and Joe headed out of London to the leafy Berkshire countryside, where they spent the day at the Origins studio. They shared insights into their journey — from being the first employees at MPG to watching the team grow to over 30 — and talked about the ins and outs of the listing and buying process.

    Don’t forget to follow us on all our socials to hear more from them and stay updated on the latest in the property world!

    See you in the next one for our September wrap-up!

  • The UK Property Market & Buy-to-Let in 2025: Trends, Challenges, and Opportunities

    The UK Property Market & Buy-to-Let in 2025: Trends, Challenges, and Opportunities

    The UK property market has long been a pillar of wealth creation and financial security. In 2025, property investment still holds strong appeal — but the game is evolving. Economic shifts, regulatory changes, and changing buyer and tenant habits are shaping a very different playing field from just a few years ago.

    Whether you’re a portfolio landlord or just starting out, understanding today’s market trends is essential for making confident, profitable decisions. Here’s a breakdown of the five key forces shaping UK property and buy-to-let this year.

    1. Economic Headwinds, Market Resilience

    The UK economy is in a delicate balancing act. Inflationary pressures remain, while interest rates — though stabilised — are still higher than many investors were used to in the 2010s.

    • Base rate: Bank of England rates have plateaued, but mortgage affordability is still under pressure.
    • Buy-to-let rates: Fixed deals currently sit around 5–6% for most borrowers (Uswitch), cooling some demand.

    Yet despite the squeeze, property values have held up in many areas. A chronic housing shortage continues to underpin prices, with ONS data showing 3.3% annual price growth as of November 2024. Performance varies regionally, with growth strongest where employment and infrastructure investment are on the rise.

    2. Soaring Demand in the Rental Sector

    With affordability challenges pushing home ownership further out of reach for many, rental demand is booming.

    • Rental growth: UK rents jumped 9% year-on-year to December 2024 — far outpacing average wage growth.
    • Tenant priorities: Remote and hybrid working have shifted demand towards properties with home office space, strong internet, and access to green areas.

    Suburban, semi-rural, and commuter belt towns are increasingly attractive to tenants — and therefore investors — due to their blend of lifestyle appeal and urban connectivity. For landlords, these areas often offer better yields and lower entry costs than major city centres.

    3. Regional Hotspots & Diverging Markets

    The UK property market is increasingly fragmented by location:

    • London: Still a magnet for global capital, but price growth is slower compared to regional cities.
    • Northern Powerhouses: Manchester, Leeds, and Liverpool are delivering standout rental yields — Manchester averaged 6.5% in April 2024, with some areas reaching 12%.
    • Scotland: Edinburgh and Glasgow combine competitive entry prices with strong demand, though landlord regulations are more stringent.
    • Coastal & Tourist Markets: Cornwall, North Wales, and other staycation destinations remain lucrative for short-term lets.

    The lesson? Local insight matters more than ever. Yields, demand drivers, and growth potential vary hugely from postcode to postcode.

    4. Sustainability & the EPC Challenge

    Green compliance is no longer optional — it’s law. By 2030, rental properties must have an EPC rating of C or above.

    • For older stock: Landlords are retrofitting properties with better insulation, double glazing, and energy-efficient heating systems.
    • For new builds: Many already meet EPC requirements, reducing long-term compliance risk.

    While upgrading can be costly upfront, ignoring EPC requirements could hit rental viability in the future.

    5. Tech-Driven Investing & Management

    Technology is reshaping property investment in three big ways:

    1. Market intelligence – data-driven platforms provide real-time insights for smarter decisions.
    2. Portfolio management – proptech tools streamline rent collection, maintenance, and reporting.
    3. Access to investment – fractional ownership models and online consultancies open the door for more investors.

    For time-poor landlords, these solutions cut admin, improve returns, and help scale portfolios with less hassle.

    The 2025 Market in a Nutshell

    The UK property market this year is a mix of challenges and openings. Yes, higher borrowing costs and regulatory demands add pressure — but strong rental demand, regional growth hotspots, and tech-enabled investing create real opportunities.

    For investors, the winners in 2025 will be those who:

    • Match their strategy to local market realities.
    • Future-proof against regulation (especially EPC changes).
    • Leverage technology to invest smarter and manage more efficiently.

    The fundamentals are still there — it’s just a matter of playing the new rules well.